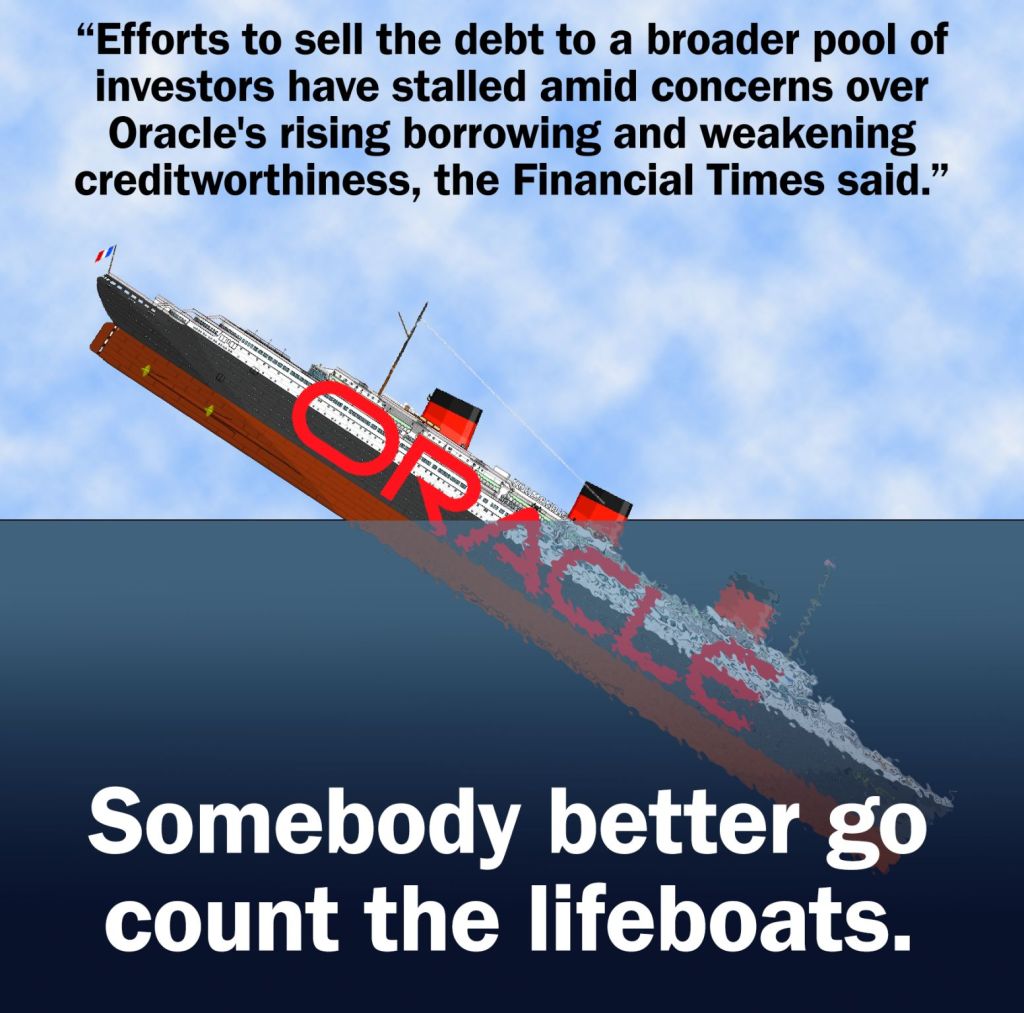
October is coming, and October is the month the stock market traditionally does very bad things. If I were Oracle, I would be dreading October.
In April I wrote about how Oracle was using legal but very sketchy accounting gimmicks to keep billions of dollars of debt off their balance sheet.
In July I wrote about how Oracle’s free cash flow was a negative 5.4 billion dollars at the end of Q2.
In August I wrote about how Oracle’s credit rating had been dropped to BBB-, which is the last ‘investment grade’ rating. Anything lower is considered junk.
Now, in September, the Financial Times is reporting that Oracle’s debt is priced at about $0.90 cents on the dollar due to fears about their high debt and low creditworthiness.
My prediction is that before the end of the year, I will be writing that:
– Oracle’s credit rating is on Negative Watch;
– Oracle’s banks have begun calling loans and demanding cash;
– Oracle’s credit rating has fallen to junk status;
– Oracle has burned through all its remaining cash; and fatally
– Oracle is having trouble moving its commercial paper.
When they can’t move the commercial paper, the ship sinks. Then we have to hope that the suction of Oracle’s sinking doesn’t swamp the other hyperscalers. If they go down, it will make 2008 look like a “minor correction.”
 Ethical Bankruptcy: Gradually, Then Suddenly
